
Newmarket Real Estate, October 2026: More Homes Sold, Prices Still Waiting
Tuesday Nov 17th, 2026
Newmarket market update · October 2026
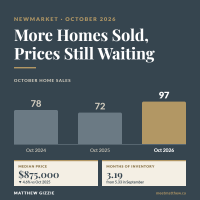
Sales jumped 52% from September and 35% from last October. Prices did not follow, at least not yet.
By Matthew Gizzie, REALTOR® · Keller Williams Realty Centres · November 2026
Homes sold
97
▲ 52% vs Sep · ▲ 35% vs Oct 2025
Median price
$875,000
▼ 0.3% vs Sep · ▼ 4.6% vs Oct 2025
Months of inventory
3.19
from 5.33 in September
Median days to sell
20
from 28 in September
The real story is turnover
October’s average sale price moved higher in Newmarket, to $946,455. The conditions behind that price matter more than the headline.
The number that stands out is the pace at which supply was absorbed. Newmarket finished October with 306 active listings and recorded 97 sales. Reported months of inventory fell from 5.33 to 3.19: more homes sold while fewer new ones arrived.
More sales, less new supply
Newmarket · October 2025 vs September 2026 vs October 2026
Newmarket regained ground after September’s slowdown. That is the context I would put around this month’s price headlines.
Newmarket regained ground
Newmarket recorded 97 sales, up from 64 in September and 72 last October. That is an increase of about 52% month over month and 35% year over year, making it Newmarket’s strongest October for sales since 2021.
New listings declined from 239 to 193, active listings fell from 341 to 306, and reported months of inventory improved from 5.33 to 3.19. Median listing days on market shortened from 28 to 20. Several measures moved in a favourable direction together.
Newmarket monthly sales
January 2024 to October 2026 · Octobers highlighted
Newmarket months of inventory
January 2024 to October 2026 · lower means homes are absorbed faster · Octobers marked
The strongest evidence: semis and freehold townhouses
The best support came from semis and freehold townhouses. Sales rose from 16 to 28 while new listings stayed at 47. That is useful evidence, because the improvement came from more transactions while the flow of new listings held steady. Months of inventory in the segment fell from 4.63 to 2.18.
Those 28 sales were also close to the historical October average of roughly 30. This part of Newmarket looks much closer to a normal October than the broader sales total suggests.
Semis + freehold townhouses: more sales, same new supply
Newmarket, September vs October 2026
Detached recovered, with distance still to travel
Detached sales recovered from 38 to 57, but the longer history keeps that in perspective: it was still the fourth-lowest October detached count since 2010. Overall, Newmarket’s 97 sales were the sixth-lowest October total, and active listings were the fourth-highest.
My reading
There is a meaningful improvement here, with some distance still to travel.
Prices: better turnover is not price pressure
The pricing evidence is more restrained. The average sale price rose 2.2% from September to $946,455, but the overall median was essentially unchanged at $875,000. Detached and semi/freehold townhouse medians both edged lower.
| Property type | Oct sales | vs Sep | Median price | vs Sep | vs Oct 2025 | Months of inventory |
|---|---|---|---|---|---|---|
| Detached | 57 | ▲ 50.0% | $1,030,000 | ▼ 1.1% | ▼ 4.6% | 3.52 |
| Semis + freehold townhouses | 28 | ▲ 75.0% | $791,000 | ▼ 1.1% | ▼ 6.1% | 2.18 |
| Condo townhouses | 7 | ▲ 40.0% | $635,000 | ▼ 0.8% | ▼ 22.3% | 3.86 |
| Condo apartments | 4 | flat | $455,000 | ▼ 7.5% | ▼ 10.8% | 5.25 |
My reading
I would describe October as a better month for getting homes sold. Sustained price pressure is a separate question, and the current figures do not establish it.
Condo apartment figures rest on 4 sales, so treat their price change as noise rather than trend.
The three-month view
October was not a one-off. Across August, September and October combined, Newmarket sales were about 4% above the same period last year, and January to October is up about 5%. The improvement in turnover has been building, which is more useful than any single month’s price comparison.
Newmarket sales vs the same months of 2025
Three windows ending October
Rental market
Leases
72
75 in Sep · 92 in Oct 2025
Average rent
$2,637
▲ 3.3% vs Sep · ▼ 6.2% vs Oct 2025
Median rent
$2,575
▲ 3.0% vs Sep · ▼ 11.2% vs Oct 2025
Active rental listings
165
158 in Sep · 186 in Oct 2025
Leasing activity eased. Newmarket recorded 72 leases in October, compared with 75 in September, and below last October’s 92. Reported rents improved from September, but Newmarket remains noticeably softer than a year ago: the average rent of $2,637 is down 6.2% year over year and the median is down 11.2%. These are blended figures across different properties, so be cautious about reading them as the rent achievable on an individual home.
For investors, particularly those with variable borrowing costs, that backdrop matters more after the latest rate decision. There is less room to assume rising rental income will absorb higher financing costs.
Borrowing costs and the economy
Bank of Canada policy rate
2.50%
Up from 2.25% on October 28. Door left open to more.
5-year Government of Canada yield
3.51%
End of October, from 3.69% end of September. 3.46% on Nov 10.
Unemployment, October
6.7%
Canada, up from 6.5%. Ontario 7.3%, up from 7.0%.
Inflation, September
3.1%
Up from 3.0% on gasoline. Excluding gasoline: 2.2%.
The Bank of Canada increased its policy rate from 2.25% to 2.50% on October 28 and left open the possibility of further increases. That is a material change from the holding pattern of recent months, and it makes the outlook for variable borrowing costs less supportive.
The bond market moved differently. The five-year Government of Canada yield declined from 3.69% at the end of September to 3.51% at the end of October, then stood at 3.46% on November 10. The timing matters: the average five-year yield across October was essentially unchanged from September, so the lower month-end figure is not evidence that financing became steadily cheaper through the month. Lower bond yields can help fixed-rate mortgage pricing, but lenders’ funding costs and margins also shape the rates borrowers actually receive.
Employment has not provided a convincing offset. Canada’s employment was essentially unchanged in October after large declines in August and September. National unemployment rose from 6.5% to 6.7%, and Ontario’s from 7.0% to 7.3%. The large monthly job losses stopped, but a meaningful rebound has yet to arrive.
Inflation needs careful reading. September’s headline rate rose from 3.0% to 3.1%, driven by gasoline. Excluding gasoline it eased from 2.4% to 2.2%, and the main core measures also declined. The Bank’s concern is that persistent energy and input costs spread into a broader range of prices, which is why softer employment has not automatically translated into easier policy.
For housing, the result is an awkward combination: fragile employment confidence, upward pressure on variable borrowing costs, and only recent relief from the bond market.
The federal budget
Since October closed, we have also had the November 5 federal budget. Its housing measures belong in the outlook, particularly for construction and investment.
One of the more practical changes is expanded access to insured financing for eligible new three- and four-unit properties, plus provisions for private mortgage insurance on buildings with five to fifty self-contained units. The new parameters apply to mortgage-insurance applications submitted from February 1, 2027, and could help the feasibility of some future projects.
The budget also proposes extending the ban on foreign purchases of existing homes to January 1, 2029, while exempting newly built homes. Those changes still need legislative and regulatory implementation. The distinction would steer more of that investment toward new supply.
These measures could influence what gets financed and built over time, depending on implementation and actual projects. For the local resale market heading into winter, employment, mortgage costs and the ability to absorb existing listings remain the more immediate influences.
What this means in Newmarket
For sellers
October makes the comparable sales in your own property category especially important. Better turnover gives well-positioned listings a better chance of finding a buyer, particularly among semis and freehold townhouses. Pricing still has to respect a median that has not moved.
For buyers and investors
There is still room to negotiate, but the purchase needs to work at current financing costs and current achievable rents. A higher average price, a lower bond yield on a particular day or a new budget announcement is not enough on its own to settle that decision.
Want this read on your own home or purchase?
The comparable sales in your own property type matter more than any town-wide headline this month. I can pull them for your street and run the numbers at today’s financing costs.
Full Newmarket market reportNewmarket rent reportMatthew Gizzie, REALTOR® · Keller Williams Realty Centres
The Economics of Real Estate · meetmatthew.ca · 905-895-5972
Data note. Housing figures are from HabiStat Historical Stats (all standard residential types, “Exclude Other Property Types” on), retrieved November 12, 2026. September comparisons reflect HabiStat’s updates since last month. Historical rankings refer to Octobers from 2010 through 2026. Sale dates follow HabiStat’s closing-date convention. Rents are blended across the property mix, not like-for-like. Economic figures: Bank of Canada (October 28, 2026), Statistics Canada Labour Force Survey (October 2026) and Consumer Price Index (September 2026), Budget 2026 (November 5, 2026).
This article is general market commentary, not financial, legal or mortgage advice. Speak with a qualified professional about your own situation.


Post a comment